Your Gateway to Elite Forex Deals
Discover exclusive broker promotions, powerful trading tools, and insights to trade smarter.
Offers Worth Your Attention
Hand-picked promotions, cashback, and risk-protection deals - updated monthly by our team.
ForexDealsPro Cashback
Up to $11 back per lot, via XM
- Paid on every trade, win or lose
- Automatic, no claims needed
- Real, verified rebate rates
- No extra cost to trade
1st Trade Secured
Covered up to $100, via TradeRise
- Loses? You get covered
- Wins? You keep the profit
- No minimum deposit required
- One-time offer per account
No-Deposit Bonus
$30 free to trade, via XM
- No deposit required to start
- Trade real market conditions
- Withdraw eligible profits
- Sign-up takes under 5 minutes


Get Paid on Every Trade You Make
Earn rebates on every trade you execute. Cashback rates are transparent, automatic, and paid straight into your account.
All Broker Promotions
All current promotions · Filter by broker below
Brokers Review
Regulated, reviewed, and independently rated - compare in seconds
Broker Comparison Table
Regulated, reviewed, and independently rated - compare in seconds
| Broker | Est. ▲ | Spread EUR/USD ▲ | Min. deposit ▲ | Regulation | Platform | Trustpilot Rating ▲ | Action |
|---|
Best Forex Brokers by Country
Regulated brokers that accept traders in your country — hand-picked by region, with local deposit methods and the best deals for each market.


MT4/MT5 Indicators & Expert Advisors
A growing library of professional MT5 indicators and Expert Advisors, built in-house to give you a genuine trading edge — and many are free to download.
Cashback - The Smart Way to Reduce Your Trading Costs
You earn on every trade.
Regardless of the outcome.
Cashback is a rebate paid on the spread or commission of every trade you execute - whether the trade wins or loses. It's the only trading benefit that never depends on market direction. The more you trade, the more you earn back, automatically.
How to start earning
What Moroccan Forex Traders Look For Before Opening an Account
Morocco's Retail Forex Market
Opening a forex trading account is a significant decision, and Morocco's retail trading scene has grown alongside the rest of North Africa's financial sector. Some brokers serve Moroccan clients well; others create real friction around deposits, withdrawals, or support once you're an actual client rather than a prospect. This article walks through what to check before funding an account, then compares brokers commonly used by traders based in Morocco.
Morocco's regulatory starting point is genuinely different from several other African markets covered on this site. The country runs a long-standing system of foreign exchange controls administered by the Office des Changes, which shapes how residents can move money abroad and hold foreign currency in the first place, a point that matters before any broker comparison does. The next two sections cover that framework and how Morocco's financial regulators divide responsibility.
If you're new to forex generally, our What Is Forex Trading guide is a good place to start, and our wider Forex Trading in Africa 2026 guide covers how North Africa fits into the continent's growth trend. For broker-by-broker detail, see ForexDealsPro's dedicated Morocco broker page.
1. Regulation and Trustworthiness
Two Moroccan bodies matter here, and, as with other markets covered on this site, they cover different things. Bank Al-Maghrib, the central bank, conducts monetary policy and manages the dirham's exchange rate regime, a fixed rate set daily against a euro/dollar basket weighted 60% EUR and 40% USD, with a trading band of plus or minus 5% around that central rate[1]. That's a monetary-policy function, not broker oversight.
Online retail forex and CFD trading instead sits under the Autorité Marocaine du Marché des Capitaux (AMMC), Morocco's capital markets regulator, established by Law 43-12, with a stated mandate covering protection of invested savings, investor information, and the integrity of the capital market[2]. Publicly available AMMC information doesn't describe a dedicated domestic licence category for retail forex/CFD brokerage, so a Moroccan trader using an internationally regulated broker is, in practice, dealing with an entity outside the AMMC's direct oversight.
A Moroccan trader's actual broker is therefore typically regulated elsewhere: commonly under CySEC, the FSCA, the FCA, or ASIC, rather than under a Morocco-specific licence. That doesn't make the broker automatically untrustworthy; it's standard practice across brokers serving markets without a local retail forex licence. What matters more is a broker whose wider group holds regulation in multiple credible jurisdictions, checked directly on the regulator's own public register rather than taken from the broker's own marketing.
Before depositing, check:
- The exact legal entity name in the sign-up terms
- Its regulator and licence number, verified directly on the regulator's own register
- Whether that same entity is the one named in your client agreement
- Whether the AMMC has published any public notice naming the platform, covered further down
2. Currency Controls and the Office des Changes
This is the section that makes Morocco meaningfully different from several other African markets ForexDealsPro covers, and it's worth reading carefully before anything else here.
Morocco operates a system of foreign exchange controls administered by the Office des Changes, a government body separate from both Bank Al-Maghrib and the AMMC. Holding foreign currency and moving money across Morocco's border isn't automatically unrestricted for residents the way it can be in some other jurisdictions.
Foreign-currency bank accounts at Moroccan banks are, per the Office des Changes' own published rules, available to foreign nationals (resident or non-resident) and, under a separate status, to Moroccans officially registered as living abroad (MRE). The published framework ForexDealsPro reviewed does not describe blanket access for a Moroccan national resident in Morocco[3].
For money leaving Morocco for personal purposes, the Office des Changes publishes an annual allowance known as the dotation touristique. Under the General Instruction on Foreign Exchange Operations effective January 1, 2026, it totals up to 500,000 dirhams per person per year: a base allowance of 100,000 dirhams for any resident adult without an income condition, on presentation of a passport and national ID, plus up to 400,000 dirhams more calculated from 30% of the income tax paid the previous year[4].
That allowance is designated for foreign travel and related personal expenses. The Office des Changes materials ForexDealsPro reviewed don't describe a specific rule covering deposits to an offshore forex or CFD broker, and this article doesn't state one either way. That's a genuinely different situation from Nigeria, Kenya, or Ghana, none of which operate an equivalent capital-control regime. Before funding any offshore trading account from Morocco, confirm the current rules directly with the Office des Changes and your own bank, rather than relying on a broker's website or a forum post.
3. Easy and Fast Onboarding
A broker can look right on paper and still lose you at the first step if verification takes days or asks for documents that are awkward to provide. A slow, confusing sign-up process is reason enough on its own for a trader to give up before ever placing a trade. Before committing, ask support directly how long verification usually takes and whether a Moroccan national ID or passport is accepted on its own.
4. Deposit and Withdrawal Methods
Moroccan traders typically fund broker accounts differently than traders in several other African markets this site covers. Mobile money, the dominant method across much of West and East Africa, isn't the standard route here, given the currency-control framework covered above. Brokers that work for Moroccan clients most commonly support:
- International bank transfer, subject to the Office des Changes rules described in the previous section
- Debit or credit card payment (Visa or Mastercard issued by a Moroccan bank), where the broker accepts it
- E-wallets such as Skrill or Neteller, on brokers that support them
Confirm current options on the broker's own deposit page, since availability varies and can change, and check whether a method carries a fee on the broker's side, separate from your bank's or the card network's own charges.
Trading accounts are typically USD-denominated, so the dirham/USD rate on the day of a deposit or withdrawal affects how much trading capital a MAD payment converts to. Bank Al-Maghrib's own published reference rate is a useful independent check[1].
5. Trading Costs: Spreads, Commissions and the Fees That Don't Make the Homepage
A broker advertising the tightest headline spread isn't automatically the cheapest once every fee is accounted for. Spread, commission, overnight swap charges, and withdrawal fees all affect what a trade actually costs.
What actually matters is the full cost to open, hold, and close the positions you intend to trade, not any single number in isolation. That distinction matters more the more often you trade, or the longer you tend to hold positions overnight.
6. Minimum Deposit and Account Types
Brokers commonly advertise minimum deposits of $5 to $20, though the exact minimum varies by account type, payment method, and jurisdiction. That's useful for trading real money without risking much while you're still learning, but a low minimum deposit isn't the same as having enough capital to trade a given strategy responsibly, a point worth keeping alongside the risk-management section further down.
7. Trading Platform and Mobile Access
For traders who manage their accounts from a phone, a broker's mobile app quality isn't a minor detail; it's a real practical priority. MetaTrader 4 and MetaTrader 5 remain the most widely used platforms, and most brokers also run their own apps alongside them. Our MT4 vs MT5 guide covers the real differences if you're deciding between the two.
Confirm the broker actually offers what you need: MT4, MT5, or its own app, and whether it's available on both iOS and Android. Then test it on a demo account first. Check how quickly orders execute, whether charts load properly on your network, and whether the app holds up during a volatile session rather than freezing at the worst possible moment.
8. Customer Support, Tested Before You Need It
French and Arabic are both widely used in Moroccan business and customer-service interactions, so checking language support in either is worth doing rather than assuming. What actually varies most is how clearly and quickly support answers a specific question about your account or a withdrawal, not whether a broker advertises round-the-clock support.
Some brokers run a regional team serving MENA clients directly; others handle everything through international channels. If responsive support matters to you, test it yourself before depositing: exchange a few messages with support and see how consistently they respond, rather than taking a support badge at face value.
9. Leverage, Risk Tools and Protections
Leverage is one of the first things Moroccan traders compare between brokers, since it determines how large a position you can open with a given amount of capital. But a bigger number isn't automatically better: leverage increases both potential gains and potential losses in equal measure, so more of it just means less margin is required to open the same position, which can tempt you into a position too large for your actual risk tolerance. Your position size should come from your own risk limit and stop-loss distance, not the leverage cap on offer.
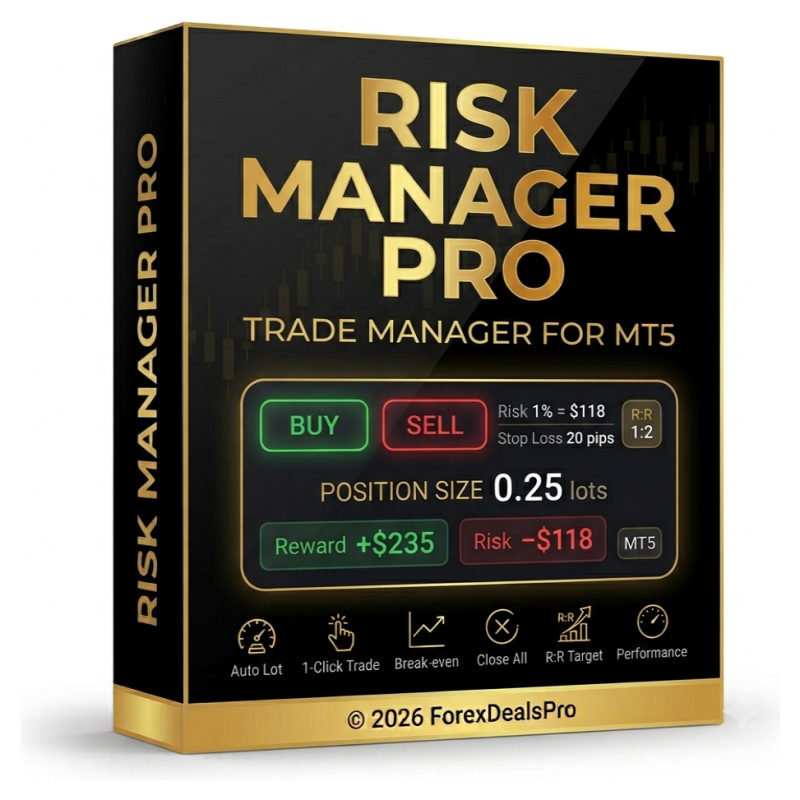
Our Forex Risk Management guide covers position sizing around a defined percentage of account risk, and ForexDealsPro's free Risk Manager Pro indicator calculates position size automatically from your chosen risk percentage and stop-loss distance.
Beyond the leverage figure, compare what's available if something goes wrong: whether client funds sit in a segregated account, whether negative balance protection applies, and whether an investor-compensation scheme applies to the specific entity and jurisdiction holding your account, not just the broker's brand. Good brokers also give you tools to manage risk yourself: adjustable leverage, stop-loss and take-profit orders, and margin alerts.
10. Reputation and AMMC Warnings
Talk to other traders before you commit. Forums, community groups, and recent reviews from people trading from Morocco can surface real patterns a broker's own marketing never will, especially around withdrawals. Not every complaint is the broker's fault, but a genuine pattern across several unrelated people matters more than one frustrated post.
In a public notice dated December 22, 2025, the AMMC warned the public against unauthorized financial investment advisory activity and a growing number of fraudulent trading platforms, many operating through social media and private messaging groups[5]. The notice pointed to buy or sell recommendations circulating online, often presented as disinterested advice, and noted that unauthorized investment advisory activity is regulated under Law 19-14 and can carry criminal penalties. It recommended verifying the identity of anyone offering investment advice and checking the AMMC's own published list of authorized advisors before acting on anything.
The notice covers investment advice broadly rather than naming specific forex or CFD platforms, but the underlying habit applies to any broker: checking claims against the AMMC's own published information before depositing is a quick, low-effort step the AMMC has explicitly asked the public to make.
Always deposit through the broker's official website, app, or payment method listed in your account portal, never through a link sent by an "agent" or a contact on WhatsApp or social media claiming to process payments on the broker's behalf. Impersonation and fake broker sites are a real risk, and money sent outside the broker's own official payment channel is very difficult to recover.
Test With a Small Deposit Before Committing More
Once you've gone through the checks above, there's still a real difference between a broker looking right on paper and working well in practice. A demo account is useful for getting familiar with the platform, but it runs on simulated pricing, not real liquidity, so it can't show you real execution, slippage, or fill quality.
A small real deposit shows you instead how the deposit process behaves given Morocco's currency-control framework, how support responds to a real question, and how fast a withdrawal actually processes. Fund a small amount first, before committing what you intend to trade with.
Some brokers also run promotional offers that can help with this. XM's $30 no-deposit offer, where available under its current terms, lets eligible traders experience live market conditions without depositing their own money first. TradeRise's first-trade offer works differently: it covers your first live trade up to $100 under the offer's stated terms, so you can test a real deposit, trade, and withdrawal with that one trade's downside capped. Read the exact eligibility conditions before relying on either.
Broker Options for Moroccan Traders
How we selected these brokers: regulatory status, availability to Moroccan traders, minimum deposit, funding and withdrawal options, trading costs, platform quality, support, and risk-management features. Our dedicated Morocco broker page has the fuller comparison and methodology. None of the four below appears in the AMMC's published warnings described above.
XM
Regulated across CySEC, FSCA, DFSA, and the CMA, with a $5 minimum deposit. See our full XM review.
IC Markets
Dual-regulated under ASIC and CySEC. Fits traders focused on execution speed and raw spreads. See our full IC Markets review.
AvaTrade
Licensed across five continents, including the Central Bank of Ireland and ASIC. Suits traders who value education and platform choice, with commission-free trading on many products. See our full AvaTrade review.
PUPRIME
Regulated by ASIC and FSCA, with a $20 minimum deposit and a copy-trading feature some newer traders use to observe how other accounts are managed. See our full PUPRIME review.
High-leverage offshore brokers are another category some traders look for, offering leverage past what the four above provide. TradeRise falls into that category, regulated by the FSA in Seychelles with leverage up to 1:5000. That's a different risk category, not a better or worse one: high leverage isn't a benefit on its own, and it only becomes useful once you understand position sizing. Our full TradeRise review covers its regulatory status and terms.
There isn't one broker automatically right for every Moroccan trader. If the main draw is simply the leverage number, that's usually a sign to slow down and check the regulatory entity, withdrawal process, and real trading costs first.
Frequently Asked Questions
Trading through an internationally regulated broker isn't something individual Moroccan traders have faced prosecution for, and neither Bank Al-Maghrib nor the AMMC issues a dedicated domestic retail forex/CFD brokerage licence. Moving money abroad to fund an account is a separate question, governed by the Office des Changes' foreign exchange rules; confirm the current rules directly with them and your own bank before transferring funds.
Bank Al-Maghrib is the central bank, handling monetary policy and the dirham's fixed exchange rate regime. The AMMC is the capital markets regulator, responsible for investor protection under Law 43-12. The Office des Changes is a separate body administering foreign exchange controls, including foreign-currency accounts and how much money residents can send abroad each year.
Under the Office des Changes' published rules, foreign-currency accounts at Moroccan banks are available to foreign nationals and, under a separate status, to Moroccans officially registered as living abroad (MRE). The published framework doesn't describe blanket access for a Moroccan national resident in Morocco.
It's the Office des Changes' annual personal foreign-currency allowance, up to 500,000 dirhams per person per year under the instruction effective January 1, 2026, designated for foreign travel and related expenses. Published materials don't describe a rule covering broker deposits specifically, so confirm directly with the Office des Changes and your bank rather than assuming either way.
The AMMC periodically publishes public notices about unauthorized investment advice and fraudulent trading platforms, including a December 2025 notice about schemes spreading through social media and private messaging groups. Checking a broker's claims against the AMMC's own published notices before depositing is a quick, direct step.
Bank transfer and card payments (Visa or Mastercard issued by a Moroccan bank) are the most commonly available methods, along with e-wallets like Skrill or Neteller on brokers that support them. Mobile money, common in other African markets, isn't the standard funding route in Morocco. Confirm current options and any transfer rules on the broker's deposit page and with your own bank.
References
- Bank Al-Maghrib: Reform of the Exchange Rate Regime: bkam.ma — Reform of the Exchange Rate Regime
- Autorité Marocaine du Marché des Capitaux (AMMC): Missions: ammc.ma — Missions
- Office des Changes: Comptes en devises: oc.gov.ma — Comptes en devises
- Office des Changes: FAQ — Quel est le montant de la dotation pour voyages personnels ?: oc.gov.ma — Dotation pour voyages personnels
- AMMC: Conseil en investissement non autorisé, plateformes de trading frauduleuses — l'AMMC appelle à la vigilance du public (December 22, 2025): ammc.ma — Public Notice: Unauthorized Investment Advice and Fraudulent Trading Platforms
Regulatory information was checked against publicly available sources from Bank Al-Maghrib, the AMMC, and the Office des Changes as of August 2026. Rules and rates can change, so verify current details directly with the relevant body before depositing or transferring funds.
About Us
Your trusted gateway to elite forex deals, broker reviews, and smarter trading.
What We Do
We research, verify, and curate the best broker deals, cashback programmes, and trading promotions available in the market, updated regularly so you always have access to what is current and relevant. Alongside our deals, we publish independent broker reviews built on objective criteria: regulatory standing, trading conditions, platform quality, and client protections.
Who We Are
ForexDealsPro is run by a dedicated team of trading and finance professionals with over a decade of combined market experience. That hands-on knowledge informs everything we publish, from the brokers we feature to the way we explain complex trading concepts in plain language.
We operate as an affiliate information platform. We earn a commission when you open an account through our links, at no additional cost to you. This model allows us to keep the platform free, independent, and focused entirely on trader value.
Our Standards
- We only feature brokers regulated by recognised financial authorities
- Every deal and promotion is verified before publication
- Broker ratings are independent and never influenced by commercial relationships
- Affiliate partnerships are always disclosed transparently
Our Editorial Process
All articles published on ForexDealsPro are thoroughly researched using primary regulatory sources, industry reports, and reputable financial publications, then verified for accuracy before publication. Our editorial team holds combined experience in forex trading, financial analysis, and compliance.